


China’s recent economic performance has brought an increasingly pressing question to the forefront of policy discussions in Beijing: how to give growth a much-needed boost in the short term. GDP growth slowed to 4.3 per cent in the second quarter before recovering modestly to 4.5 per cent in the third.
Following the disappointing second-quarter economic data, the Communist Party of China’s Politburo met on July 30 and called for stronger countercyclical measures and greater efforts to expand domestic demand, including through the development of the so-called “six networks”: water networks, new-type power grids, computing power networks, next-generation telecommunications networks, urban underground utility networks, and logistics networks. On August 28, the National Development and Reform Commission (NDRC) convened a nationwide meeting to arrest the decline in investment, directing officials to accelerate major infrastructure projects, including the six networks. The agency followed up in early September with more detailed arrangements for project financing and implementation.
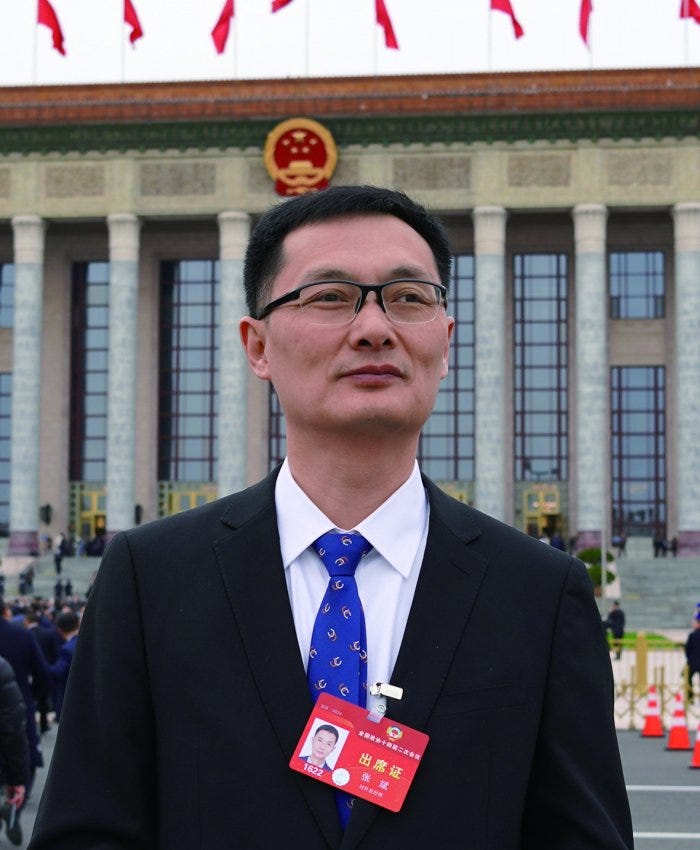
Against this backdrop, Zhang Bin, Deputy Director of the Institute of World Economics and Politics at the Chinese Academy of Social Sciences, makes a broader case for public investment. He argues that despite China’s already extensive infrastructure network, there remains considerable room for investment in public services, affordable housing, and the maintenance and upgrading of existing facilities. Such spending, he contends, can break the vicious cycle of weak demand, slowing income growth, and declining expenditure.
Zhang also challenges the assumption that greater government borrowing would necessarily aggravate China’s debt problems. He argues that slower debt growth can depress incomes and actually push debt ratios higher, whereas debt-financed public investment, by stimulating growth and improving debt repayment capacity, could ultimately help reduce the economy’s overall debt ratio.
The article was published on 1 October 2026 by Sanlihe, an online commentary platform affiliated with China News Service, as part of a series examining China’s investment trends. Zhang has agreed to this translation.
扩大内需仍需公共投资挑大梁
Public Investment Must Still Take the Lead in Expanding Domestic Demand
The key to expanding domestic demand is to use a powerful external force to break the vicious cycle of falling income, spending, expectations, and credit. China’s past experience shows that increasing public investment can be an effective way to achieve this. By substantially boosting business and household incomes in a short period, government investment has helped break this vicious cycle and put the market back on track.
Such investment has not only stimulated domestic demand but also played a crucial role in improving living standards, upgrading industries, and protecting the environment over the longer term. It has been an important driving force behind China’s economic miracle.
Public investment still has much to offer today, both in driving domestic demand and laying the foundations for future development. Borrowing to finance additional public investment does not necessarily increase debt risks. On the contrary, if used appropriately, it can help reduce them.
Public investment is the key external force needed to stimulate domestic demand
When domestic demand is weak, income growth slows for businesses, households, and governments alike, prompting each to cut back on spending. This can easily create a vicious cycle: one person’s spending is another person’s income, so when everyone cuts spending, income across the economy falls. The resulting downturn then reinforces itself. This is a classic example of market failure, which market forces alone are unlikely to resolve.
The key to expanding domestic demand, therefore, is to introduce an external force capable of breaking this cycle, getting the market back on track and restoring economic vitality.
Public investment can provide precisely this external force. When demand is weak, public investment has two important advantages over market-driven spending. First, public investment decisions are made independently by the government, which is not bound by the usual market logic of cutting expenditure when income falls. Second, the government can mobilise substantial investment in a relatively short period, sharply increasing business and household incomes and powerfully reversing the downward momentum generated by market forces.
China’s experience offers several examples. In 1998, a major infrastructure investment programme, centred on the development of a nationwide expressway network, helped the economy overcome weak demand. In 2008, China’s RMB 4 trillion infrastructure investment package helped the economy achieve an early V-shaped recovery from the global financial crisis. In 2015, government support for the redevelopment of shantytowns helped revive the property market and credit growth, pulling the economy out of another period of weak demand.
A substantial increase in public investment leads to a marked recovery in income growth across the economy, which in turn boosts workers’ earnings and consumption. Past experience shows that public investment and consumption are not competing forces. Rather, they reinforce each other. When demand is weak, public investment is one of the most effective ways to address market failure, revive economic activity, and stimulate growth in workers’ incomes and consumption.
China still has ample scope for public investment
China has invested heavily in infrastructure, including electricity and gas networks, railways, roads, airports, ports and terminals, and has made remarkable progress. In many areas, its infrastructure is now on a par with, or even ahead of, that in developed countries. But this does not mean that the opportunities for further public investment have been exhausted. There is still much to be done to improve living standards, upgrade industries, and protect the environment.
In terms of new investment, there is considerable scope to expand public facilities and services in areas such as education, culture, sport, underground utility networks, and urban roads. China still has fewer libraries, museums, and sports facilities per million people than developed countries. Some 110 million migrants living in the urban areas of prefecture-level cities and above struggle to establish permanent homes in the places where they live. Local governments lack sufficient affordable housing, schools, and healthcare facilities to meet their needs. These shortfalls point to substantial unmet demand for public investment.
As for existing infrastructure, China has traditionally placed greater emphasis on building new facilities than on maintaining, repairing, or rebuilding those already in place. Decades of construction have left the country with an enormous stock of public infrastructure, much of which could be made considerably safer, more effective, and more convenient to use. Significant additional investment is needed to ensure that these facilities can fulfil their potential.
Public investment has a distinctive role in addressing problems that ordinary people and businesses face but struggle to resolve, even when they are willing to pay. It does not take much looking to find such problems in everyday life. As long as public investment is guided by the needs of ordinary people and businesses, there will be no shortage of worthwhile projects to invest in or work to be done.
The government has not borrowed excessively, and more borrowing for public investment need not increase debt risks
International experience shows that, over the past two decades, government borrowing has accounted for approximately 49 per cent of the total increase in debt across advanced economies. The corresponding figures are 58 per cent in the United States and 74 per cent in Japan, compared with just 34 per cent in China. These figures use the Bank for International Settlements (BIS) definition of government debt, which covers not only official government debt but also some hidden local government debt.
Strong demand for Chinese government debt among domestic and foreign investors suggests that they consider it relatively safe and are not generally concerned about its sustainability. Some local governments face unsustainable hidden debt burdens, but this does not mean that the government sector as a whole has borrowed excessively.
Several rounds of debt swaps and other debt resolution measures have substantially reduced local governments’ hidden debt, but a large amount remains outstanding. Many local governments lack the fiscal resources to meet principal and interest payments on their own. Countercyclical policies, including greater public investment and lower policy interest rates, can help correct market failures and restore economic vitality. They can also ease the debt burden on local government financing vehicles through several channels: increasing local tax revenues and land transfer sales, boosting the revenues of financing vehicles and the value of their assets, and reducing borrowing costs. Over time, these measures could help alleviate local government debt problems, particularly in more economically developed areas and those attracting population inflows.
Concerns about an overly high macroeconomic leverage ratio have led some to argue that borrowing should be kept to a minimum to reduce debt ratios and debt risks. This reasoning is broadly sound for individual households and businesses, because borrowing less may have little effect on their income growth, allowing their debt ratios to fall.
But the situation is very different for a country as a whole. Slower debt growth across society generally goes hand in hand with slower income growth, meaning that the debt ratio may actually rise rather than fall. Between 2002 and 2025, the correlation coefficient between debt growth and the debt ratio in China was -0.49, indicating that slower debt growth was associated with a rising debt ratio.
The United States, the euro area, and Japan have seen similar patterns. In recent years, debt has expanded rapidly in these economies, yet their debt ratios have gradually declined, demonstrating a negative correlation between debt growth and debt ratios.
The lesson is that by borrowing to expand public investment and thereby raising income across the economy, China can reduce rather than increase its overall debt ratio, strengthen its capacity to service debt, and keep debt risks under better control.
Zhang Bin: China still needs more investment

The East is Read has previously published extensively on China’s domestic-demand debate, which centres on a basic question: when demand is weak, should policy focus primarily on boosting consumption, or should investment take the lead in raising employment, incomes, and ultimately consumption?