

Over the weekend of September 19, the 2026 Tsinghua People’s Bank of China School of Finance (PBCSF) Chief Economists Forum was held at Tsinghua University, themed “China and the Global Economy in 2026: Review and Outlook — Global Rebalancing and Re-Architecturing of the International Monetary System.”
The Tsinghua PBCSF Chief Economists Forum is an annual event hosted by Tsinghua PBCSF, formerly the official graduate school of China’s central bank, and organized by its Center for International Finance and Economics Research (CIFER). (I had the privilege of being selected for the PBCSF-Bank of China Finance & Media Scholarship/Fellowship Program in its 9th cohort between 2021 and 2023.)
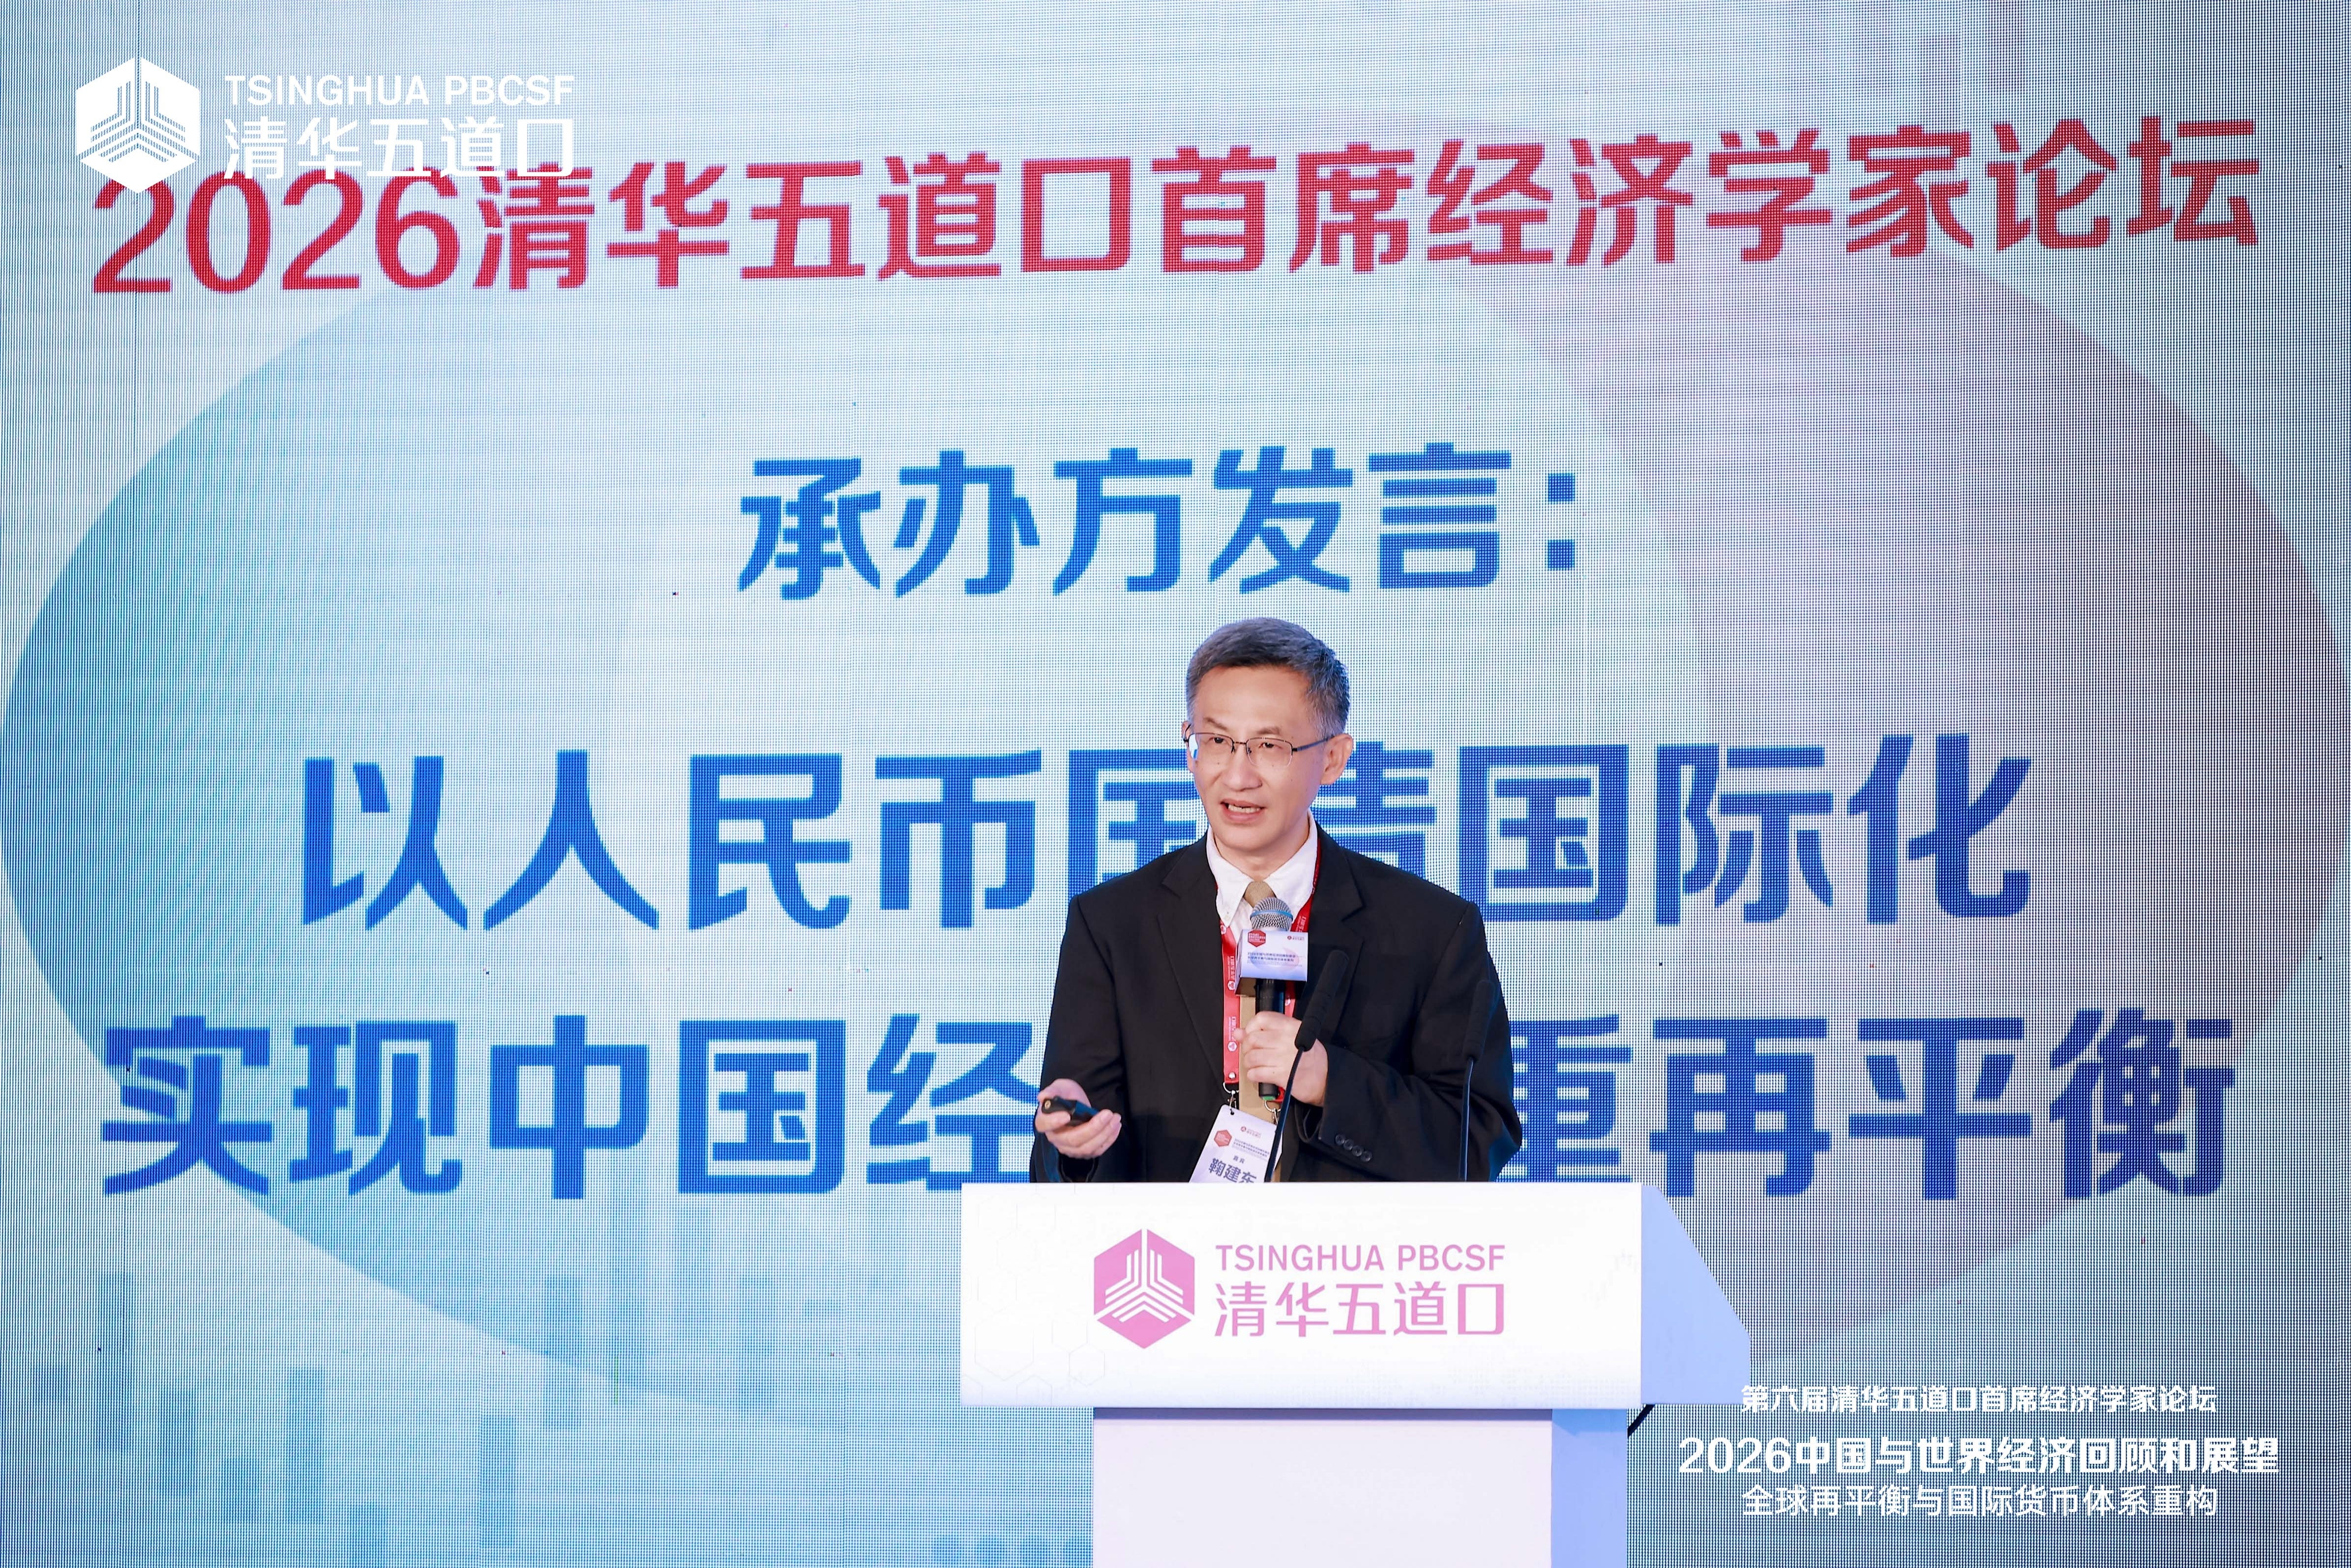
Ju Jiandong, Unigroup Chair Professor at the PBCSF, Tsinghua University, and also organizer of the star-studded forum and head of the CIFER, delivered a speech in which he put forward an analytical framework and policy proposal for achieving China’s triple economic rebalancing through the internationalization of RMB government bonds.
Yingshi “Fred” Gao has, in his Inside China substack, published a partial transcript of Ju’s forum, including competing remarks from a Ju-moderated panel discussion by Justin Yifu Lin, Yu Yongding, Yao Yang, and Li Xunlei, the biggest names in China’s public debate on economic policy.

Below are the key points Ju shared in his keynote speech
Ju pointed out that the three structural contradictions are interrelated and mutually reinforcing, and that the issuance of RMB-denominated government bonds to overseas investors by the central government is a policy tool that can deliver all three rebalancings at once.
China’s Economy Faces Three Structural Contradictions
The external structural contradiction in manufacturing — China’s manufacturing surplus is large and continues to expand. In 2025, China’s current account surplus reached US$735 billion, of which the goods trade surplus was about US$1.2 trillion, and it has continued to widen recently.
In Ju’s view, sectoral economies of scale (externalities) exist in both manufacturing and finance: the larger a sector, the more efficient its firms. Following the logic of Ricardian division of labor, decades of international specialization have led China and the United States to concentrate on their respective industries of advantage. China, as the manufacturing center, produces and exports manufactured goods, which gives rise to its manufacturing surplus. The United States, as the financial center, absorbs international capital, and the corresponding capital inflows into the U.S. appear on the books as China’s trade surplus and America’s trade deficit. The so-called China–U.S. trade imbalance is the natural outcome of market-based division of labor and cannot be simply attributed to China’s subsidies, exchange rate, or other policy distortions.
The domestic structural contradiction between supply and demand — domestic demand is insufficient to fully absorb manufacturing supply. China is transitioning from an industrial society to a welfare society, yet pension and basic service provision for low-income households has not been adequately established, and household consumption remains weak. The property market downturn has further depressed domestic demand, pushing more manufactured goods to seek markets through exports. In 2025, China’s final consumption (household consumption plus government consumption) accounted for 56.9% of GDP, the lowest among major economies — compared with 85.27% in the United States, 72.72% in Japan, 75.71% in Germany, 82.57% in Brazil, and 67.44% in India. Take pension insurance as an example: in 2024, the average monthly pension for urban and rural residents was RMB 249.4. Ju estimates that raising the monthly pension for urban and rural residents to RMB 1,000 (about four times the 2024 level) would entail a funding gap of RMB 1.59 trillion.
The structural contradiction between central and local public finance — the central government still has fiscal space, while local governments face more pronounced fiscal and debt constraints. Local public finance has long relied on land sale revenues and debt financing. Since the property market downturn, revenue from the transfer of state-owned land use rights fell to RMB 4.15 trillion in 2025, down 14.7% from the previous year, and local governments have increasingly relied on debt rollover and borrowing new debt to repay old debt to sustain operations. Meanwhile, in 2024 China’s central government debt stood at 25.6% of GDP — markedly lower than Japan’s 200.9%, the United States’ 102.7%, the United Kingdom’s 100.7%, and Germany’s 44.0% — meaning the central government still retains considerable room to borrow.
Traditional external adjustment paths, however, can hardly resolve these contradictions. Ju pointed out that if China were to rely on RMB appreciation or trade measures to narrow the surplus, export competitiveness would decline, manufacturing employment would come under pressure, and the effect of any surplus adjustment would be uncertain — the structural surplus would not necessarily disappear as a result.
Internationalization of RMB Government Bonds Promotes China’s Triple Economic Rebalancing
Ju Jiandong put forward three core conclusions:
First, how can China’s external assets and liabilities be rebalanced? The US$1.2 trillion trade surplus implies a US$1.2 trillion increase in China’s net foreign assets. To rebalance assets and liabilities, one approach would be for China to reduce its foreign assets by US$1.2 trillion — that is, to sell off US$1.2 trillion of foreign assets (mainly U.S. Treasuries) — but such a sell-off would jolt the global U.S. Treasury market. The alternative is for China to increase its external liabilities by US$1.2 trillion, equivalent to RMB 10 trillion, offsetting the US$1.2 trillion increase in net assets. A simple and feasible way to do this is for China to issue RMB 10 trillion of government bonds to overseas investors, thereby rebalancing China’s external assets and liabilities.
The proceeds from the RMB 10 trillion of government bonds issued overseas can be spent in three areas: RMB 2 trillion to raise the average monthly pension of urban and rural residents to RMB 1,000; RMB 4 trillion to swap for (newly incurred) local government debt — that is, using the bond proceeds to purchase local government debt, so that local governments can use the funds to increase local government investment; and RMB 4 trillion for new central government investment.
Second, the RMB 2 trillion used to raise the monthly pension of urban and rural residents will increase their income and boost consumption demand; the RMB 4 trillion for local government investment will increase local investment demand; and the central government’s RMB 4 trillion can be invested in strategic industries such as AI and new energy, increasing the central government’s investment demand. The new demand generated in these three areas will substantially raise aggregate domestic demand and achieve a rebalancing of the macroeconomic supply-demand structure.
Third, using RMB 4 trillion of government bonds to swap for local government debt leverages the central government’s sound fiscal space to ease local governments’ debt pressure, support local fiscal expenditure, and promote local government investment, thereby achieving a rebalancing of central and local public finance.
Issuing RMB 10 trillion of government bonds to overseas investors can also accelerate the internationalization of the RMB and provide safe assets for the world. At present, the global supply of safe assets (US$40 trillion of U.S. Treasuries) has almost reached the ceiling of U.S. Treasury issuance. The internationalization of RMB government bonds comes at exactly the right time.
In Ju’s view, rebalancing China’s economy involves long-term structural reform, which faces considerable resistance and difficulty. It is rare to find a single policy that can simultaneously accommodate the interests of China and the rest of the world, of urban and rural areas, and of central and local governments — and the internationalization of RMB government bonds is precisely such a policy initiative, one that takes all parties’ interests into account and approximates a Pareto improvement.

Ju Jiandong reimagines the Chinese local state: a new blueprint for Chinese modernisation

Ju Jiandong, Chair Professor at PBC School of Finance, Tsinghua University, and Deputy Director of Tsinghua University National Institute of Financial Research, has recently argued that the future of the world’s second-largest economy lies in institutionalising its 2,000 counties into legitimate, corporate-like “holding companies”—the kind to be listed …
Tsinghua scholar advocates progressive carbon tax in China

This is the fourth newsletter from Pekingnology of a series of speeches made by guest speakers at the 2021 Tsinghua PBCSF Economic Forum on Carbon Neutrality held on September 16.
Thank you, Zichen, for bringing this to English so quickly. The forum rarely travels beyond Beijing, and Professor Ju has done something unusual here: one policy aimed at three imbalances at once. The ambition deserves a careful reading.
One point on the accounting, offered in that spirit. A bond sold to a foreign investor for cash adds a liability and an asset of the same size. China's net foreign assets still move with the current account. The financing changes the mix, not the total, so the "offset" works for gross holdings but not for the net position.
The inflow then has to land somewhere. Some Chinese resident ends up holding the matching foreign asset, whether the PBoC, the banks, or private investors abroad, or else the yuan rises until the surplus shrinks. The first path piles up more of the foreign assets Professor Ju is trying to rebalance away from. The second is the adjustment he says will not work.
The domestic half is the stronger half, and it is strong. Moving local debt onto the central balance sheet and lifting residents' pensions stand on their own. Neither needs a foreign buyer.
And that buyer will ask what reserve managers always ask. Can I leave on a bad day? Can I hedge in size? Whose court hears the dispute? Since February 2022, when roughly $300 billion of Russian reserves were frozen, they ask it of every issuer.
Interesting idea. Consolidating local debt is necessary anyway and won't really change the overall indebtedness. Creating an international debt market would help making the CNY a global reserve currency. The part about pensions, however, doesn't add up. paying 1000 Yuan monthly, or 12000 Yuan yearly to say 200 million elderly Chinese would cost 1.2 T per year! The proposed 2 T would be gone in less than two years, and what then?